Retirement isn't one number. It's three.
Ever been at a barbecue when the conversation turns to retirement?
Someone talks about when they plan to stop working. Someone else mentions how much they have in super. Then a figure gets thrown into the conversation.
“You need at least a million.”
One person feels relieved. Another goes quiet and starts wondering whether they’re far behind.
You might even feel a little smug because your balance is higher.
But the comparison isn’t much use.
Your friends may have paid off their home while you’re planning a renovation. You may want to travel several times a year. They may prefer holidays closer to home. Perhaps you want to help your children, keep working two days a week or leave money behind.
The number only means something when we know what you want it to pay for.
That’s why I find it more helpful to think about three retirement numbers.
1. Your enough number
What does enough mean to you?
Start by picturing an ordinary week in retirement.
Where are you living? How are you spending your days? Are you working at all? Eating out? Playing golf? Looking after grandchildren? Planning your next trip?
Then consider the larger expenses that may come along.
Will the house need work? When might you replace the car? Do you want to help your family? Are there hobbies or travel plans that will cost more in the first few years?
Some people want a busy retirement with regular overseas travel. Others want more time at home, a few local trips and the freedom to see friends during the week.
Your enough number starts with your version of retirement.
It won’t predict every cost for the next 30 years. Nobody can do that. It gives us a practical picture of what you want your money to support.
2. Your feel-safe number
Most people also have an amount they like to keep in cash.
We often call it an emergency fund. I also think of it as your feel-safe number.
It means the hot-water system can break, the car can need repairs or a dental bill can arrive without knocking your plans sideways.
The amount varies from person to person.
Someone may feel comfortable with $20,000 nearby. Someone else may want $100,000 before they stop checking their bank balance.
Part of that comes down to your expenses. The rest comes down to you.
Ask yourself:
How much would I want in the bank, so an unexpected expense doesn’t feel like a big deal?
It also helps to decide what the money is there for and how you would top it up after using some.
A cash buffer won’t earn the same returns as money invested for longer-term growth. But feeling secure matters too. The job is to find a balance that works for you.
3. Your safe to spend number
This is often the hardest number to judge on your own.
How much can you spend each month or year without worrying that today’s choices will leave you short later?
I meet people who have built substantial assets but still hesitate to use them.
- Can we afford the trip?
- Should we replace the car?
- Is helping the children going to cause a problem later?
- Are we spending too much?
After decades of saving, switching to spending can feel uncomfortable. A healthy super balance doesn’t automatically make that feeling disappear.
This is where financial modelling helps.
We work backwards. First, we look at what you’d like retirement to cost, including everyday spending, holidays and bigger purchases. Then we look at what you have available to support it: your super, investments, other income and any debts.
We test how those numbers work together over time, allowing for inflation and different investment outcomes, while keeping your cash buffer in view. That helps us assess whether your expected spending looks sustainable and what you may need to adjust.
- What happens if you retire next year instead of in three years?
- Could you spend more during the first decade while you’re active?
- What changes if you renovate, downsize or give money to family?
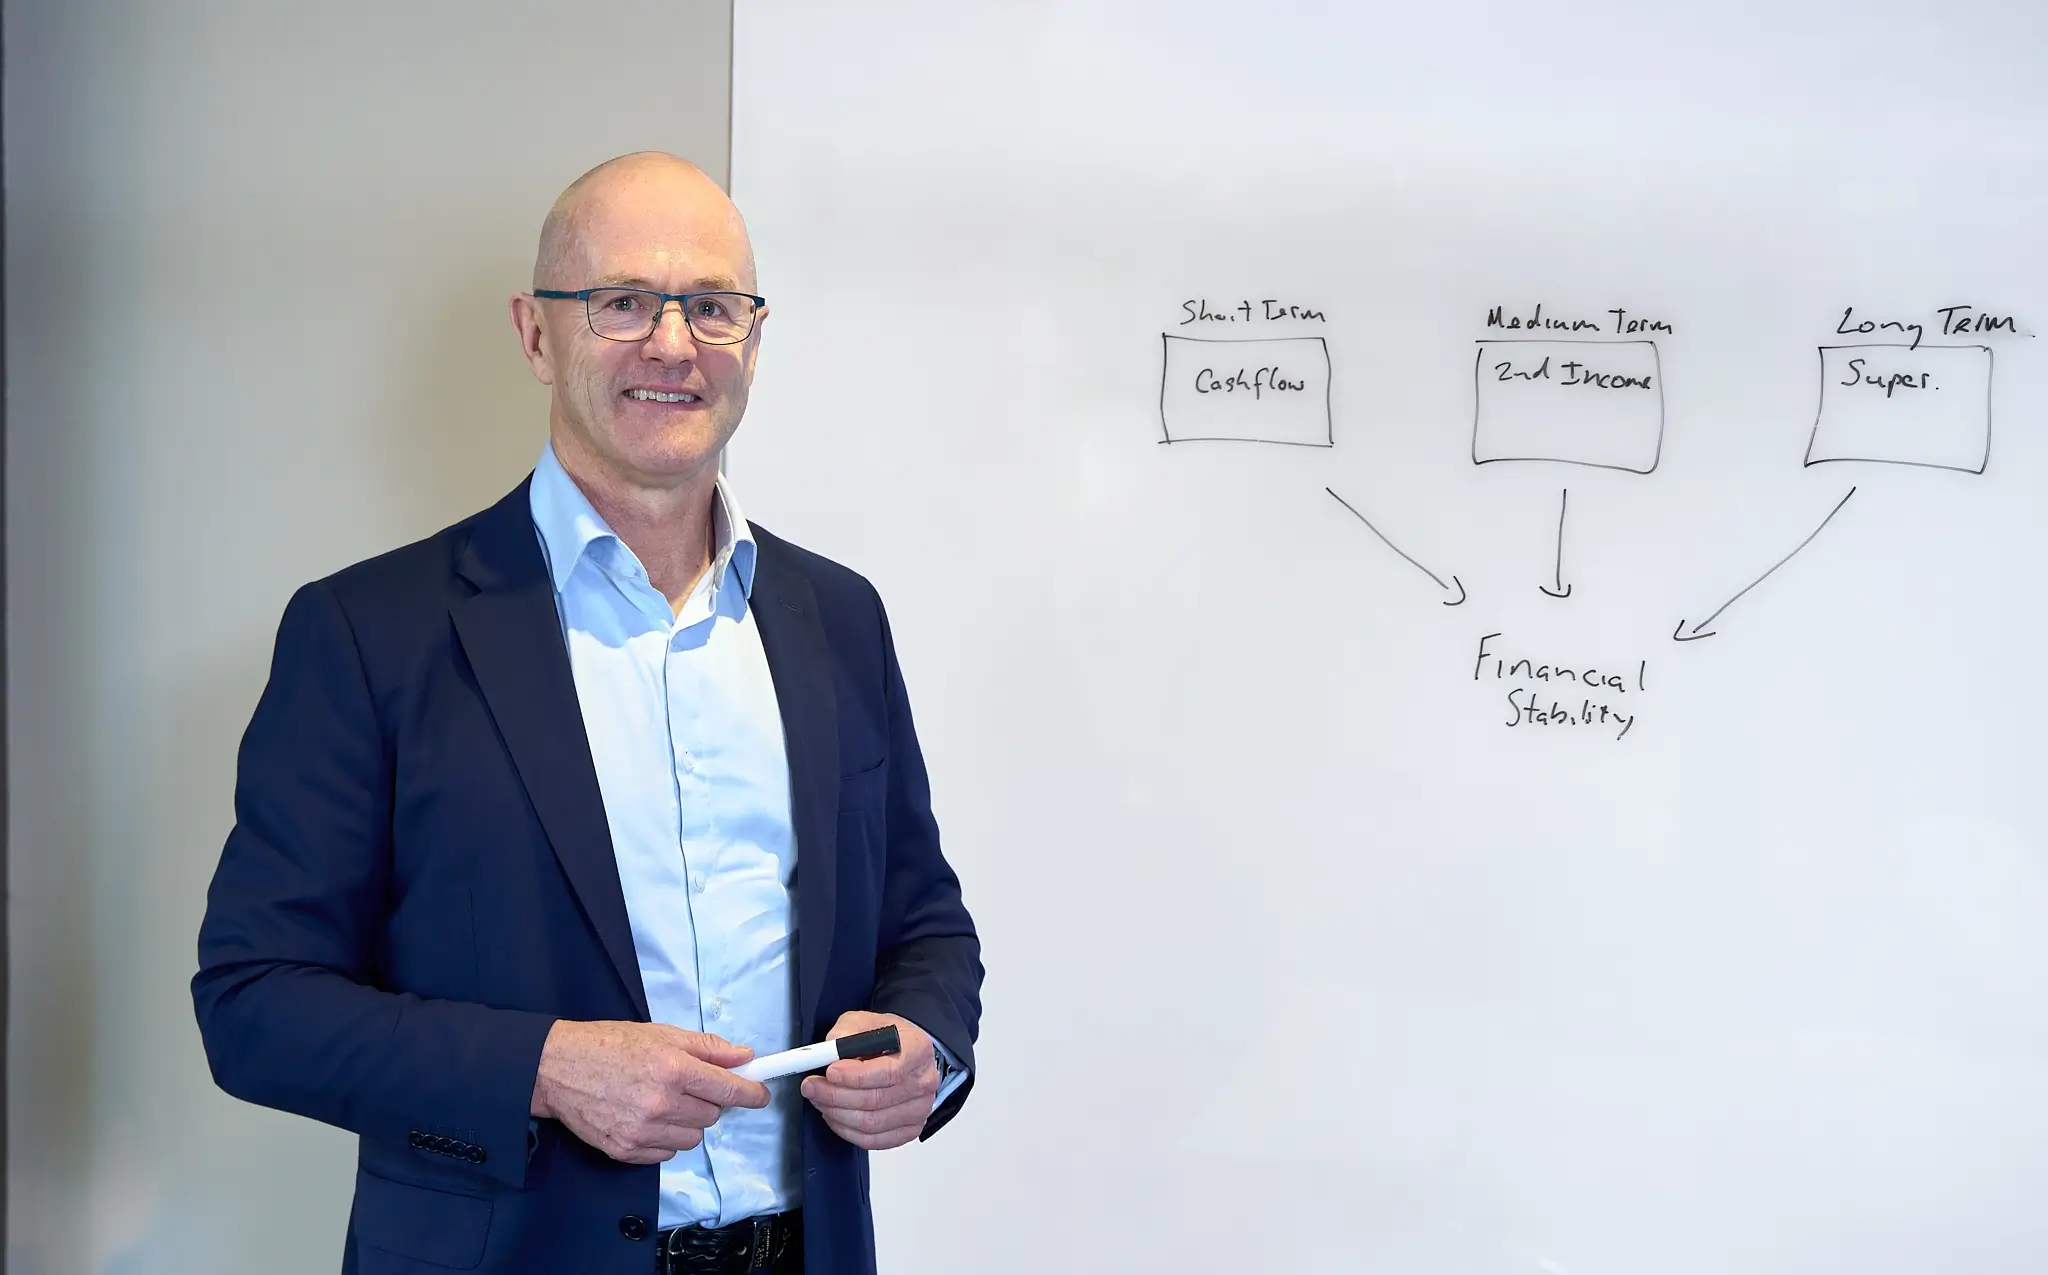
Retirement modelling can give you a sound spending range and show which choices your financial position can support without stressing you out.
That can make it much easier to book the holiday or replace the car without questioning the decision for the next six months.
A simple way to sort the decisions
Once you start thinking about retirement, the questions can pile up. When to finish work, what to do with your super, whether to renovate or move, how much you can spend and what the next 20 or 30 years may hold.
Trying to answer everything at once makes retirement feel harder than it needs to be.
Sort the decisions into four groups instead.
Decide now
These are the choices that may shape your next few years.
- When might you reduce your work hours?
- What income will you need?
- Does anything need to change with your super?
- What large costs are coming?
- How much cash would help you feel safe?
Try before you commit
Some parts of retirement can be tested.
- Live on your expected retirement income for three months
- Move to a four-day week
- Take a longer break from work
- Spend more time on the activities you expect to enjoy
- Track what an ordinary month costs
A small test may tell you more than another year of thinking about it.
Plan for later
These questions matter, but they may not need an answer yet.
- Whether you’ll downsize in ten years
- What care you may need later
- How your travel could change
- How much you want to leave your family
- What your spending may look like in your 80s
You can return to these decisions when you know more about what you want and what life looks like then.
Take care with these decisions
Some choices may be hard or expensive to reverse.
- Selling your home
- Making large gifts to family
- Taking substantial money from super
- Committing to a major purchase
- Changing how your retirement income is structured
These are the decisions worth slowing down for. Run the numbers, look at the flow-on effects and get advice before you act.
Start with three rough numbers
You don’t need a perfect retirement plan before speaking with an adviser.
Start by thinking about:
- What your chosen life may cost
- How much cash helps you feel secure
- What you would like to spend each year
Bring those rough numbers, along with the decisions currently circling in your head.
We can check what’s possible, test a few different paths and work out which choices matter now.
That’s why we ignore the BBQ number. Everyone’s idea of retirement and starting point is different. What matters is what your money needs to do for you.
Are you heading towards retirement?
Not sure of your numbers?
Want to talk with someone who understands how it works?
Book in a discovery call and we can take it from there.
Michael.
Get Money Insights direct to your inbox
Be the first to receive our monthly updates, practical strategies, and timely financial perspectives.